

Is Green Steel Within Reach in India?
Report · Transition Asia and TERI · October 2026
Green steel at India’s next primary steel plant costs 6–13% more than coal-based steel. What closes the gap sits outside the plant fence.
Full report One-page summary Model and data Slides Explore the findings
One real decision inside India’s steel expansion
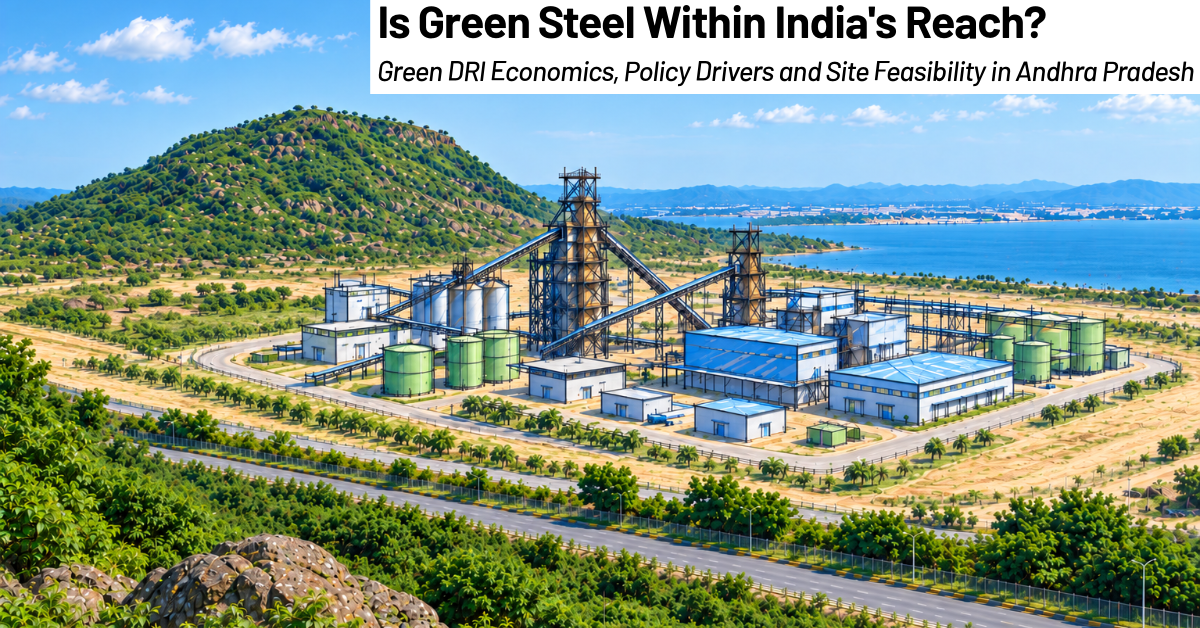
Accounting for 42% of global steelmaking capacity currently under development, India holds a major share of upcoming capacity, most of which remains to be constructed. This report evaluates a real upcoming decision: selecting the production route for Phase 2 of ArcelorMittal Nippon Steel’s greenfield complex located in Rajayyapeta, Andhra Pradesh. The investment decision for this roughly 9.6 Mtpa capacity is expected around 2030, with commissioning targeted for 2033.
Using a plant-level model tailored to local power, ore, and policy conditions, this analysis compares three direct reduced iron (DRI) production pathways, a shaft furnace using pellet and a fluidised bed and a rotary kiln using low-grade fines, against the traditional coal-based BF-BOF route, from natural gas to 100% green hydrogen.
The cost gap is no longer the main barrier
Run on 100% green hydrogen, the three DRI routes make steel for $571–606 per tonne against $536 for the BF-BOF, while emissions fall from 2.6 tonnes of CO₂ per tonne of steel to 0.3–0.6. The routes sit within $35 of one another, so the reactor is chosen on iron feed, maturity and emissions rather than headline cost. Securing hub hydrogen at $2/kg narrows the rotary kiln’s cost gap to within $5 of traditional coal-based steel, with India’s carbon market bridging the remaining difference.
Making steel: the cost of each configuration
Closing the premium: hub hydrogen, then the carbon market
Key findings
Click a finding to open it.
The green premium is modest and the routes have converged
The domestic carbon market works through the pace of its targets
What the scheme is worth to a green plant, $ per tonne of steel
The EU border helps on exported tonnes only
Hydrogen is the plan; natural gas is only a fallback
The supply risk of natural gas outweighs its cost advantage.
Procurement matters more than technology
Hub hydrogen: the largest single lever, conditional on delivery
Three conditions outside the plant fence decide the outcome
None is a technology question, and none is in the steelmaker’s hands alone.
CCTS targets and carbon price
Worth $10–45 per tonne by 2035, depending on the price, on how fast targets tighten, and on whether the scheme comes to reward new low-emission capacity directly.
Energy-banking envelope
The plant needs 470–1,555 MW of banked load against a state-wide envelope of about 700 MW. Unless it grows, or storage is supported, the bankable power structure is not available at this scale.
Hydrogen hub delivery
Pudimadaka delivering hydrogen near $2 per kg by 2032, with Phase 2’s offtake secured. With it, the rotary kiln lands within $5 of the BF-BOF route, while the plant’s debt coverage rises to 1.93 times.
What to do
AM/NS India
Commit Phase 2 to fuel-flexible DRI designed for hydrogen from the start. Report Phase 2 as a separate CBAM installation. Lock in group-captive power and utility banking before the final investment decision. Buy hub hydrogen if it delivers.
Policymakers
Publish a long-dated path for CCTS reduction targets and signal how the scheme will treat new low-emission capacity. Turn the Green Steel Taxonomy into demand. Expand the banking envelope or support storage. Deliver the hub near $2 per kg.
Financiers
Underwrite on debt coverage rather than headline cost. The steel price that holds 1.3 times cover is $590 per tonne with hub hydrogen, $611 making it on site, $662 for the self-build and $692 on third-party open access.
The decisions fall due in order
Before 2030Policymakers publish the CCTS target path and signal the treatment of new low-emission capacity, so that it is investable at the Phase 2 decision.
Before the final investment decision, 2028–30The reactor; the power structure and its 26% equity stake in the generation vehicle; the hub offtake agreement; and CBAM registration of Phase 2 as a separate installation.
2032–33Hub commissioning and Phase 2 start-up. The fuel share follows the delivered hydrogen price against the $1.70–2.11 per kg threshold.
Costs are the levelised cost of steel in 2025 US dollars per tonne of crude steel, 2030 decision year.